Translate

Thursday, June 4, 2015

The Tale of the Output Gap

The output gap, is a seldom mentioned economic statistic compared to some more readily recognizable ones like Gross Domestic Product (GDP) or Consumer Price Index (CPI), yet its implications have just as much sway over monetary policy as its better-known cohorts.

The output gap is defined as the difference between the actual output measured in GDP, and the potential output of the economy at full employment without evidence of inflationary pressure. A positive output gap refers to a period where the economy is producing above its long-term potential, and positive inflationary pressure is evident in the economy. A negative output gap refers to a period in which the economy is producing below its long-term potential, and negative inflationary pressure is evident in the economy. The Great Recession, was not the first period in American economic history where the output gap was negative, though it does stand out for its duration compared to other recessions. When it’s all said and done, the US output gap is likely to drift back into positive territory to offset the current period of a negative gap. I am interested more specifically in the overall trend unfolding in the time series of the output gap statistic.


After a short glance at the time series going back to 1949 of Output Gap data, a downward trend becomes apparent. My intuitive conclusion is that the American economy has been progressively falling behind its long-term potential for output, over the past 65+ years. This timeline coincides with the lifecycle of the Baby Boomer generation. In other words, the Industrial Revolution that occurred in the US economy leading up to the Great Depression, set the bar so high for relative expansion of production potential, that the following generation spent the sum of its working years perniciously falling short on the whole. Not to be understated, this is the generation that built on decades of industrialization to create what we now consider the difference between developed and developing economies. As a final act, the Baby Boomer generation facilitated the transition from the manufacturing centric economies of their boom years, to the service centric economies the developed world enjoys today.

The next Act is set to be as spectacular as, if not more so than, the previous Acts of the Industrial Revolution and the post World War 2 manufacturing boom seen in the developed world. The next Act is the story of the Millenials and a service driven economy that does not place a premium on labor. The x-factor in this part of the narrative is how integrated and extensive the role of technology will be in the resounding success, or epic failure of the next generation to ‘have a turn’. To the credit of the Millenials, technology is an incumbent part of their everyday existence, and integration of ideas both abstract and mundane, is second nature. The frontier of human-technology interfacing may prove to be ground upon which this next generation of entrepreneurs and problem solvers cultivates the next burst of economic expansion.


Thursday, May 21, 2015

All Good Things Must Come to an End


I’ve based most, if not all of my investment decisions around the performance and perceived outlook of the US dollar. It has certainly been a fairly consistent marker of global risk appetite versus risk aversion for as far back as I can compare financial data with the macro-economic narrative of the day. I have recently completed a full turnaround of my foreign exchange portfolio from net long dollar to net short dollar. The trading decision to turn the portfolio around was based on technical signals from my charting software, and the analysis it allows me to perform of the prices of my preferred securities. The conviction to initiate and follow through with the reversal comes from a compilation of my interpretation of my trading signals, and the evolving macro-economic environment.

My technical analysis of the price movements of a few dollar exchange rates have highlighted several consistencies with some trading signals and the directional magnitude of the market outcome of macroeconomic data and information. Though the individual currencies in the portfolio paint their own pictures of their respective economies on the ground relative to the dollar, the index acts like a weighted average for comparison. This average represents the sum of all greed and fear in international capital markets. In a nutshell, as of recently, the signals that I have been interpreting from my technical analysis have all been pointing to international capital markets that are finding fewer and fewer reasons to be fearful of the near-term macroeconomic environment. With this easing of sentiment, the dollar will lose its allure as a safe-haven in exchange for rising foreign yields.

The picture painted by my technical analysis of my charts tends to coincide with the macroeconomic narrative that the Federal Reserve and most market commentators seem to subscribe to. It is worth mentioning that as before, the mistiming of a macroeconomic insight and a financial market decision making has left me needing to actively manage my hedging efforts while I wait for the rest of the party goers to realize the festivities are over.

Tuesday, May 5, 2015

While We Wait

The US dollar is accepted practically everywhere, and is used more than any other currency for international transactions. The US economy by most measures is still the largest and most productive economy on earth. This puts the United States in an interesting position; some might say dilemma.

When the US economy was growing at its potential and the dollar was falling, a large portion of exports generated in emerging and developing markets were either meant to be sold in the US, or processed elsewhere before being sold in the US. Inversely, those same exporters were the ones consuming the technology and intellectual property being exported by the United States. But as it currently stands, the US economy is rehabilitating from the traumatic effects of the 2008 Global Financial Crisis and resulting economic spillover. Meanwhile the dollar has been rising almost vertically for the last five years or so. This recent trend in the dollar translates to a general level of unease - - not necessarily fear - - in international financial markets. US economic data have been overall positive and improving. But with the demographic shifts that are beginning to accelerate in developed economies, along with already monumental levels of private and public debt, sources and drivers of sustainable growth are few and far between. That being said, historically the safest place has been the US dollar in times of economic uncertainty.

The current consensus is that this summer, conditions will be ideal for the Federal Reserve to begin re-adjusting its stance on loose monetary policy. This will undoubtedly be a significant signal from the Fed to US and global financial markets that the economy is once again growing on a sustainable path that can lead to a zero output gap. This signal will inevitably filter into foreign money markets and interest rates will adjust in other economies closely linked to the US. Once local prices adjust, in response to inherent sensitivity to funding costs, monetary policy in other major economies will begin to re-align as well. This scenario plays out if the signal from the Fed is reinforced by subsequent steps towards further policy tightening. This of course, can only happen if the US economy is once again growing on a sustainable path that can lead to a zero output gap.

In the meantime the dollar is beginning to consolidate, and somewhere out there, investors are positioning their portfolios for long anticipated news from the Fed on how the US economy is really doing via monetary policy signals. The Fed, in turn is waiting on signals in the economic data to discern the future of monetary policy; and in the real world, people go about their daily lives.

Monday, April 20, 2015

Not Quite Like Before: The Dollar and the US Economy at Odds


 The dollar is currently rising through levels not seen since the mid to late 1990s. That of course was a time of great optimism, inspired by a wave of economic development and expansion, not just in the US but across the globe as a whole. Since then we’ve seen the dollar peak and drop to lows made just prior to the onset of the Global Financial Crisis of 2008. Along the way, the tech bubble burst, the housing bubble burst, and finally the commodity bubble burst. The bubbles themselves representing the peak of the dollar, the accelerated decline, and reversal respectively over time. Now, the dollar is once again appreciating steadily versus the currencies of US trading partners.

On the surface, this looks like the US economy is standing out as a place where an investor can earn a reasonable return when adjusted for risk, as was possible in the late 1990s. With a few details missing this time of course. For starters, the economy is just not growing with the same enthusiasm as it did back then. Unemployment is not providing upward support for wages and consumption now as it did in the 1990s, while short and medium term inflation in not expanding providing support for interest rates and monetary. This much being obvious, the financial markets have been able to steady the course to higher prices for both stocks and bonds. Albeit, a sizable chunk of the financial asset price increases can be attributed to the mechanical requirements of administering the Federal Reserve’s Quantitative Easing programs by the Federal Open Market Committee (FOMC), the remainder can be attributed to investors underpricing risks of future price decreases by continuing to transact at the elevated price levels.

As with most aspects of human existence, this too is unsustainable. The complexity of the moving parts that influence the macroeconomic, and monetary equilibrium of an economy like that of the United States will undoubtedly continue to make deciphering a clear narrative a daunting task.

Wednesday, April 8, 2015

What Really Happens to Asset Prices?

If you subscribe to the conventional dialog about the normalization of monetary policy by the Federal Reserve, the so-called ‘lift-off’ should be this summer or thereabouts. I’m not necessarily convinced that the timing is best, but I digress. The primary result of the Quantitative Easing programs utilized by the Federal Reserve was an enormous increase in excess reserves in the banking system. A secondary effect was the run-up in financial asset prices, as a result of the open market actions of the Fed to influence the levels of long-term interest rates. Economic Commentaries from the Federal Reserve Bank of Cleveland suggest that the target of Fed tightening will be the excess reserves within the banking system, and not necessarily interest rates from the onset.

When the vast amounts of liquidity that the banks hold starts to collectively dry up due to the change in the Federal Reserve’s stance on monetary policy, the transactions that have been supporting financial asset prices will begin to slow. At that point, what happens to asset prices? Equities prices on one hand, are at record highs and likely to drift higher. Without the technical demand from the banking system, the fundamental demand in relation to household savings levels will not be enough to keep equity prices at or above current levels.  Debt prices on the other hand, are at record highs and likely to drift higher. It is important to note, that the rebalancing effects of the Federal Open Market Committee’s (FOMC) actions in the debt markets to influence long-term interest rates pushed bond prices to now elevated levels.

Quantitative Easing was a necessary evil on the part of the Federal Reserve, as doing nothing would have been even less palatable. Now, we’ve arrived to the point of dealing with the aftermath and eventual unwinding of the policies. Without the implicit and at some points explicit support of the Federal Reserve, financial markets in the US and by extension the rest of the world would be forced to stop pretending. A more realistic picture of the economy may have a chance of emerging. Monetary policy unwinding does not necessarily turn into a market crash, it would simply effect a realignment of Wall Street with Main Street.

Wednesday, March 18, 2015

Why Spend When You Can Save?

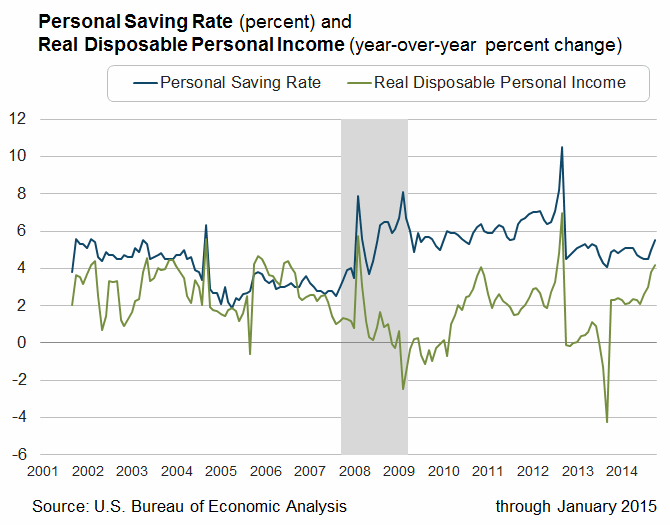
According to the most recent measure of Personal Saving Rate and Real Disposable Personal Income by the U.S. Bureau of Economic Analysis, both the Personal Saving Rate and Real Disposable Income have been trending higher in recent months. This by itself is wonderful news and should be reason for optimism. But alas, in the world of macroeconomics things are [almost] never that simple. Increases in the Saving Rate should be followed by increases in investment and consumption, though the same can be said for increases in debt. The investment side of things is underway insofar as financial markets are liquid and risk is cheap, thanks to the co-ordinated efforts of Central banks around the world. The tangible side of investment still remains elusive, as fiscal leadership no-doubt has to play a pivotal role in making those dreams a reality.


The measure preferred by the Fed for tracking inflation, The Personal Consumption Expenditures Price Index, which is also compiled by the U.S. Bureau of Economic Analysis, is already below the Federal Open Market Committee’s (FOMC) explicit objective.  The Index has been extending its trend lower in recent months. The headline measure [which includes oil] is far lower of course than the core measure which is meant to be more stable over time. The core measure is also falling, which indicates that some of the downward pressure on consumer prices is already baked into our ‘economic cake’. The irony of the situation is that what is playing out among households across the United States was first demonstrated by the commercial banks with new Fed money; they saved or deleveraged, and would only spend on investments that were high priority.


After all, the American consumer has not received a real raise in quite some time, so it would be somewhat difficult to save and consume at the same time especially since job confidence took a huge hit with the 2008-2009 recession. It is also generally agreed that American debt (both households and government) was reaching unsustainable levels leading up the Great Recession. The Fed helped the banks, the Federal Government didn’t do much, and now households are finishing the job of the public sector. Americans will continue to save until the collective urge for gratification becomes overwhelming, and then the savings accounts, retirement accounts, home equity, credits cards, and student loan money will be unleashed unto the global economy again. And of course, the banks will be there with a new and improved list of financial instruments that are guaranteed to make the world a better place.


Monday, March 2, 2015

Political Rhetoric Meets Real World Economics


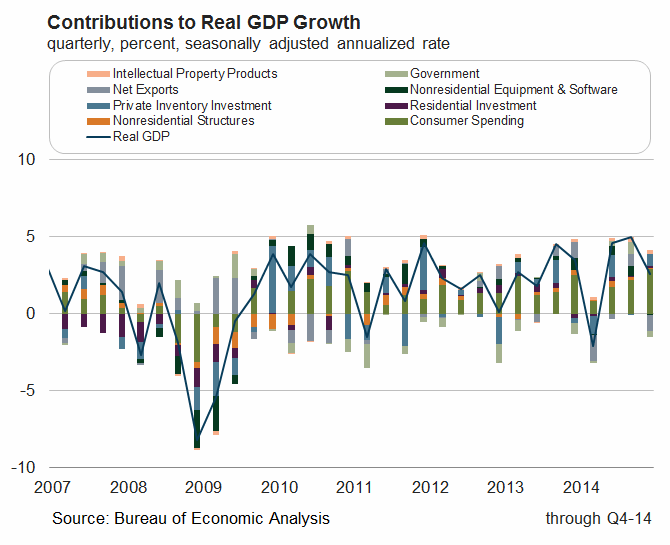
Its not very often that one gets what one wants in life, and politics is by far no exception. A strong dollar looks and sounds good from a strategic and rhetorical standpoint, but in real terms the outcomes are not always so romantic. Looking at contributions to real Gross Domestic Product (GDP) growth, which is an economic indicator compiled by the Bureau of Economic Analysis (BEA), two components stand out as having a negative impact on Real GDP growth on a quarter-on-quarter basis. Both net exports and government [spending] are down. First, net exports are down as result of an appreciating dollar that has been making domestic goods and services more expensive relative to foreign equivalents. Second, government spending is self-explanatory, as it simply spends less.


These ideologies are appealing on paper and in speeches, but in the real world they leave the US with a losing hand in globalized trade. US investors also lose the net gain from repatriating returns on foreign denominated investments that occurs when cheaper dollars bought back than were sold at the time of the initial investment. Cuts in government spending that free up productive capacity that the market cannot fill tends to cause the price of marginal units of productive capacity to fall; we see this overall effect in Real GDP, wages, and inflation expectations. There’s a time and a place for everything – or so it is said – and the US economy is the place where a globally- traded currency can appreciate with little detriment vis-a´-vis its peers. The time however, is not favorable for fiscal policies that increase rather than decrease excess productive capacity in the US economy. At least not in conjunction with the tightening monetary policy aspirations of the Federal Reserve System.